

BT Group reached a deal to buy TalkTalk after a distressed sale process, but the transaction is no longer a routine merger review. On 5 October 2026 Digital Secretary Lisa Nandy issued a public-interest intervention notice citing risks to emergency calls, hospitals, and vulnerable broadband customers if TalkTalk's networks failed. A CMA pre-emptive order from 6 October blocks integration while keeping both businesses as going concerns until the competition authority reports by 19 October—turning the buyer into a steward of a rival's live network.
TalkTalk had been shopping consumer and wholesale units after financial difficulty, DCMS said. An open bidding process failed to produce a buyer for the whole company; BT Group then agreed to acquire it. That is the commercial spine. The regulatory story is different: ministers now treat the takeover as a live-network rescue where collapse would ripple through emergency services, hospitals, schools, and customers who cannot absorb a sudden switch.
On 5 October 2026 Digital Secretary Lisa Nandy issued a public interest intervention notice under section 42 of the Enterprise Act 2002. The notice lets her weigh wider public-interest factors once the Competition and Markets Authority reports on competition. She specified grounds tied to public-health emergencies and—via forthcoming legislation—to continuity of telecommunications supply, including disruption to critical national infrastructure and vulnerable customers. The CMA must report by 19 October 2026.
Phone and broadband are vital national infrastructure. If TalkTalk services fail, there is a genuine risk to life and public services.
Nandy’s published statement framed the intervention as urgent and exceptional. DCMS stressed that customers need take no immediate action and that services should continue while the acquisition proceeds—an assurance that only matters if regulators can enforce separation between ownership and operational failure.
Hold separate, keep the lights on
The day after the intervention notice, the CMA issued a pre-emptive action order effective 6 October 2026 on BT’s completed acquisition of TalkTalk Telecommunications Limited and PlatformX Communications Limited. The order is classic merger hold-separate architecture with a public-interest twist: integration is prohibited unless the CMA consents in writing.
The addressees may not combine IT platforms, merge customer lists, transfer key staff, or pass competitively sensitive information between BT and TalkTalk. TalkTalk must keep its brand and negotiate with its own suppliers and customers. Both businesses must remain going concerns with resources consistent with pre-merger plans. Breach carries CMA penalties and, for false compliance filings, criminal exposure under the Enterprise Act.
That structure creates two parallel tracks. Track one is competition: whether BT owning TalkTalk substantially lessens competition in UK telecom markets. Track two is continuity: whether the state can tolerate any remedy that risks service disruption while TalkTalk’s finances remain fragile. Paragraph 3 of the order explicitly shields acts completed before commencement—acknowledging that stabilisation steps may already have begun—while everything after 6 October requires separation unless the CMA grants a derogation.
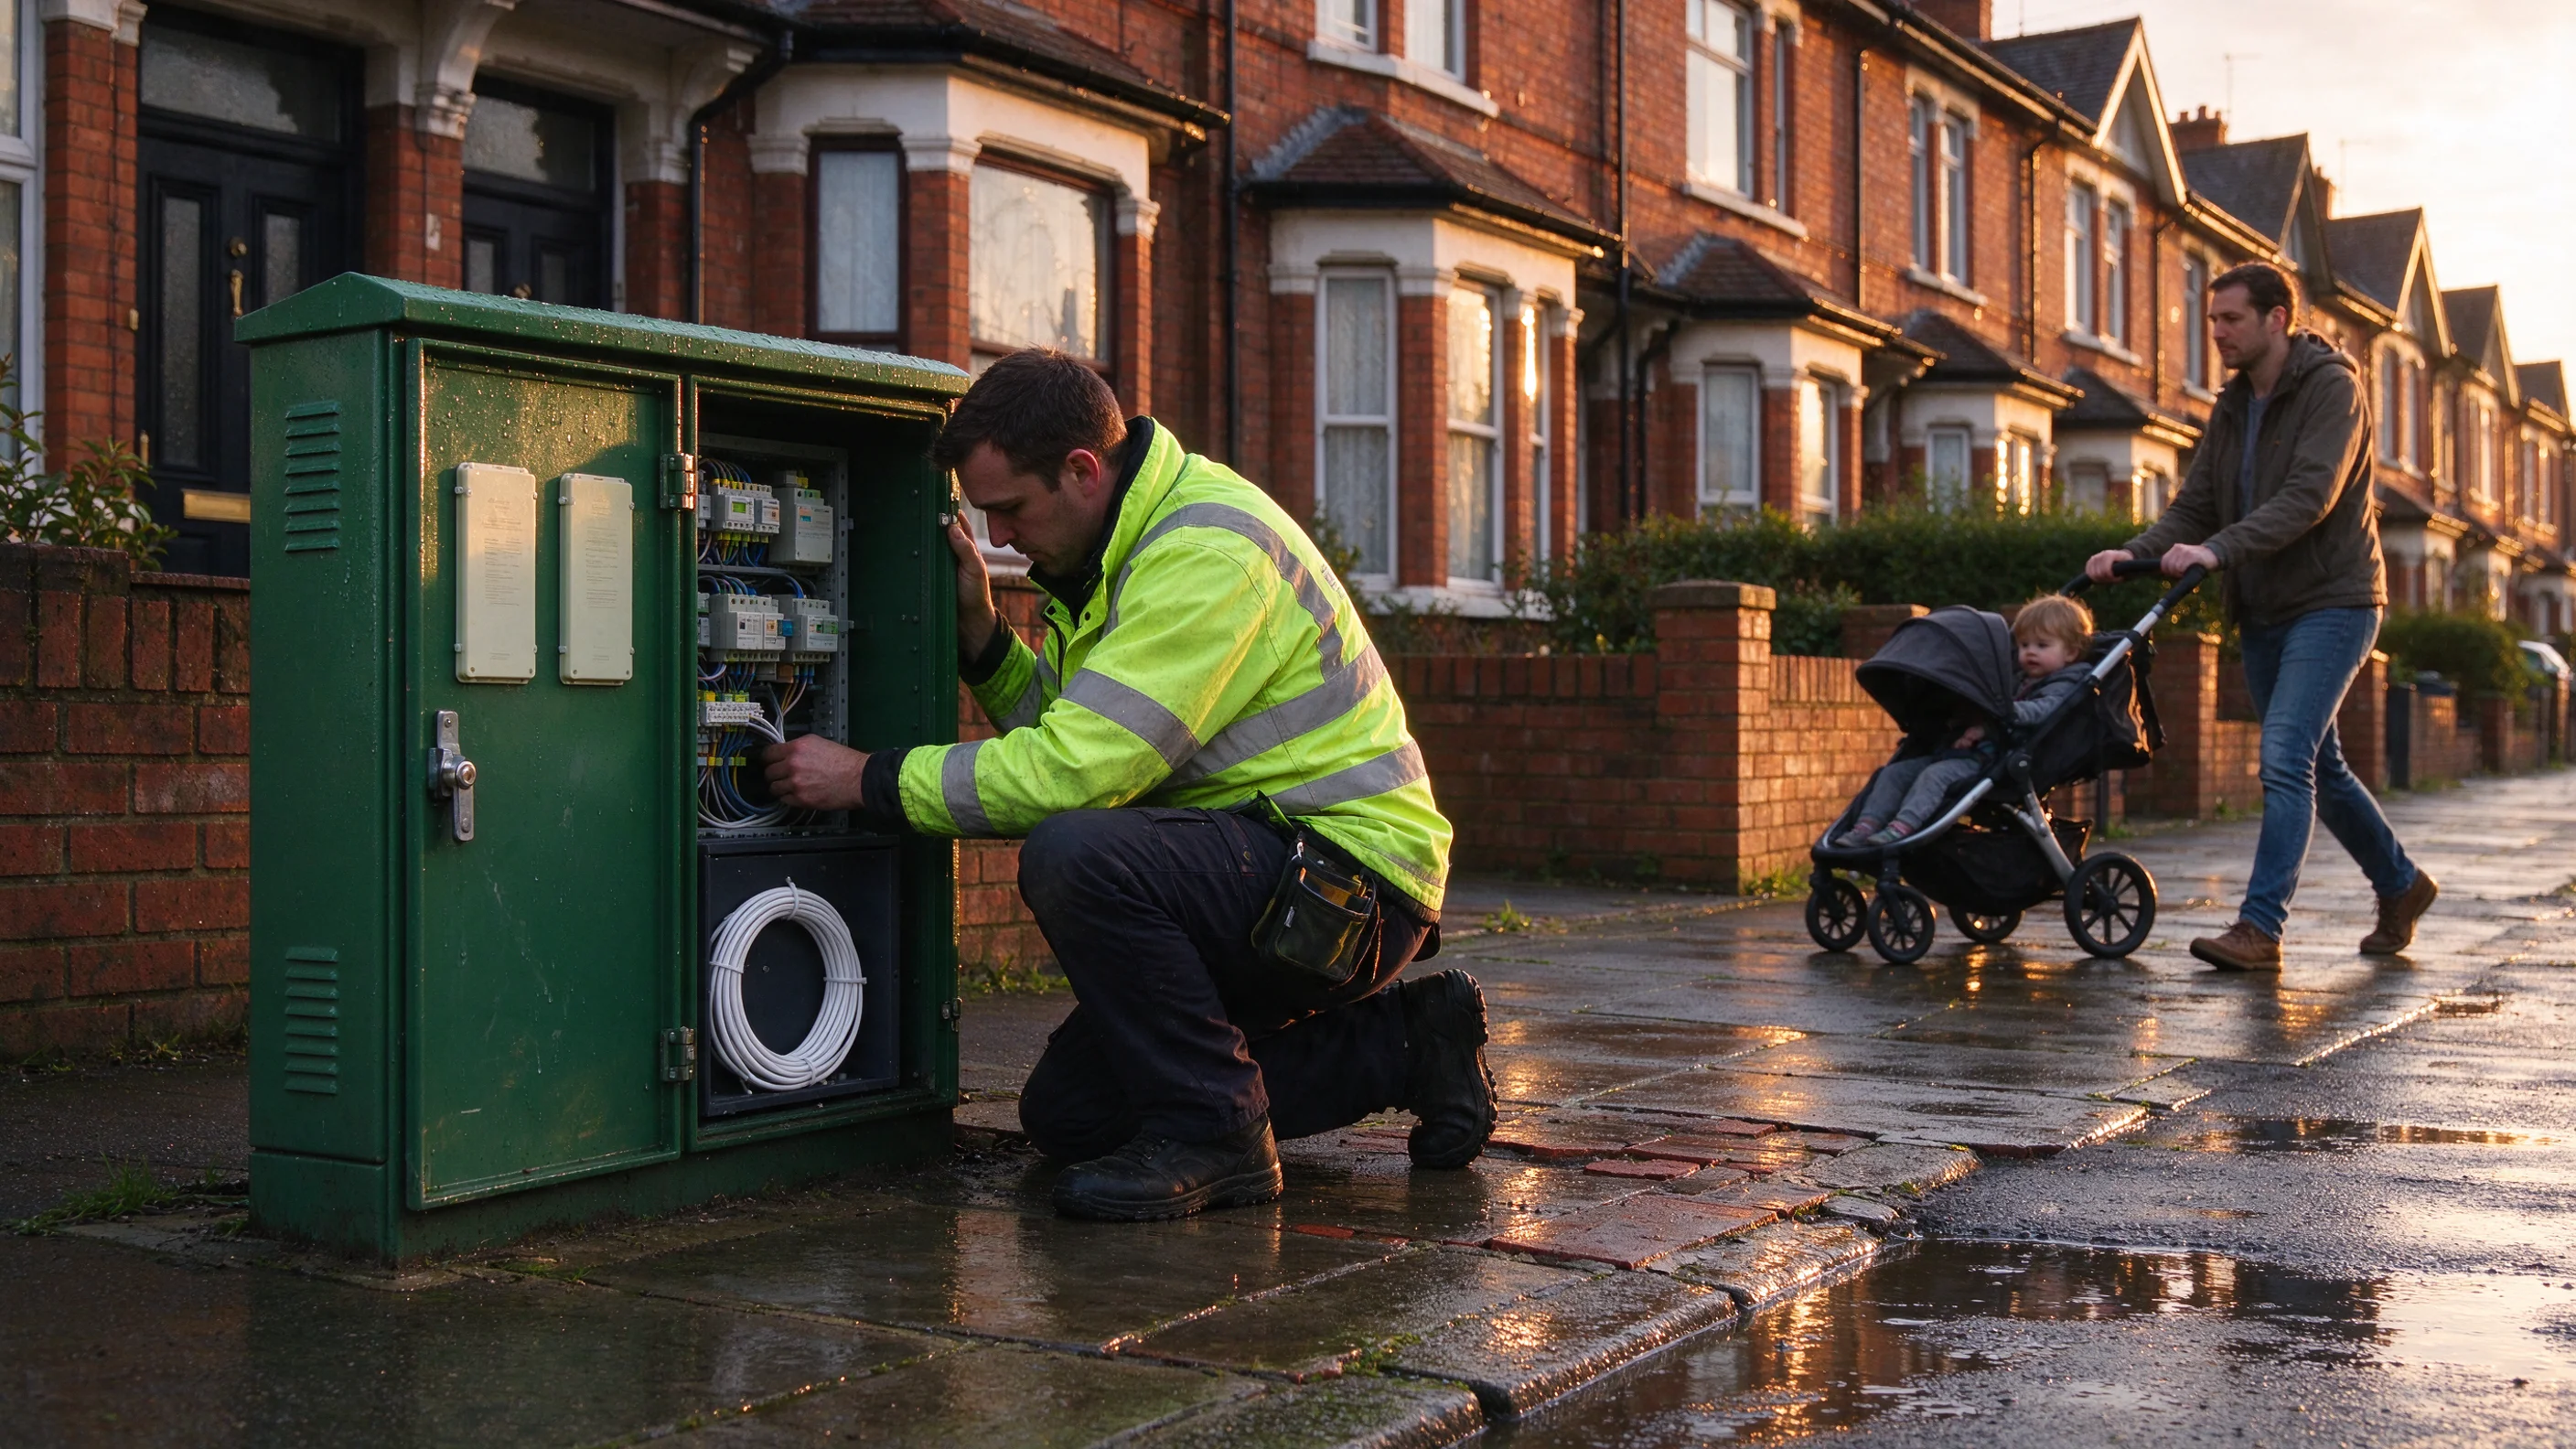
For BT, the economics of a distressed acquisition collide with the politics of being the incumbent national carrier. The buyer must fund a rival’s network without harvesting synergies on the timeline private equity would expect. For rivals, the order limits BT’s ability to rationalise overlapping retail propositions or back-office cost until clearance—or a conditioned remedy—arrives.
Why this is not the SpaceX spectrum story
Recent Culled coverage of SpaceX’s 800 MHz purchase and the FCC’s prior Starlink spectrum path tracks facilities-based wireless competition and commission transfer review in the United States. Britain’s proceeding is narrower and more civic: it asks whether a wholesale and consumer base large enough to matter to emergency routing can change hands without interrupting service. European competition law elsewhere still fights distribution and labor-market leverage; here the binding constraint is state power to pause integration until continuity evidence is on the record.
Investors should not assume the remedy is automatic clearance. The Secretary of State can accept or reject CMA recommendations, attach conditions, or refer the transaction to a longer phase-two review depending on how competition and public-interest findings align. DCMS has not published a final remedy; nor has the order confirmed whether TalkTalk experienced material outages after the sale process accelerated. The known facts are procedural: intervention, hold-separate, and a 19 October reporting deadline that falls inside the same autumn window as other telecom regulatory clocks.
What to watch before 19 October
CMA competition narrative. Market definition for retail broadband, wholesale access, and business connectivity will determine whether BT–TalkTalk looks like consolidation or salvage. Any theory of harm must coexist with the order’s mandate to preserve service quality and range.
Derogation requests. Stabilisation spending, supplier payments, or limited shared systems may require CMA consent. Each consent is a datapoint on how much integration ministers will tolerate in the name of continuity.
Public-interest legislation. DCMS said it will lay an order amending the Enterprise Act to codify telecommunications continuity as an intervention ground. The statutory text will matter for the next distressed carrier sale, not only this deal.
Service headlines. The intervention notice was preventive. Markets will punish BT if medical-alarm routing, emergency-call completion, or vulnerable-customer migrations hit the front pages—even if competition clearance eventually follows.
Britain has recast a takeover as infrastructure triage. BT may end up owning TalkTalk, but until Westminster and the CMA are satisfied, it cannot run TalkTalk like a captured rival. The open question is whether regulatory separation can keep a distressed network alive long enough for ownership to become a remedy rather than a risk multiplier.
Continue reading


Sources
DCMS 5 October 2026 intervention notice press release; CMA 6 October 2026 pre-emptive action order on BT's completed acquisition of TalkTalk Telecommunications and PlatformX Communications.


