

Target Corporation reported third-quarter net sales of $25.3 billion, down 1.5 percent year over year, with comparable sales off 2.7 percent as in-store traffic fell 3.8 percent but digital comps grew 2.4 percent on same-day delivery; adjusted EPS was $1.78 versus $1.85 a year ago, full-year adjusted guidance narrowed to $7.00–$8.00, and management pledged roughly $1 billion more in price and experience investments before holiday, so LABOR's staples-first spending pattern—not a uniform retail recession—explains why discount traffic rose while discretionary margins compressed.
Big-box retail earnings this week are less a referendum on **AI** than on who still has slack in the household budget. **Target**'s print shows staples and same-day delivery winning while general merchandise bleeds—a pattern [Culled tracked](/articles/midterm-cash-power-software-barbell-nov-4/) in the post-midterm barbell economy. The Fed minutes the same day described strength "concentrated in higher-income households"; **Target**'s basket is the other half of that sentence.
Minneapolis, Nov. 19 — Target did not miss because Americans stopped shopping. It missed because Americans shopped like the FOMC minutes said they live: staples firm, discretion optional, delivery impatient.
The retailer reported third-quarter net sales of $25.3 billion, down 1.5 percent from 2025, with comparable sales off 2.7 percent, according to its earnings release. The comp split tells the story: stores fell 3.8 percent while digital grew 2.4 percent, powered by more than 35 percent growth in same-day delivery through Target Circle 360. Food & Beverage and Hardlines—the chain’s “fun essentials” bucket—posted comp gains. The broader discretionary portfolio stayed soft.
GAAP earnings per share were $1.51; adjusted EPS was $1.78, down from $1.85 a year ago after excluding severance and asset-related charges. Operating income fell 18.9 percent to $0.9 billion including those charges; ex-items operating income was $1.1 billion. Gross margin was 28.2 percent, essentially flat, but markdown pressure rose—exactly what you expect when traffic needs a price hook.
Capital answers to labor’s mix shift
Incoming chief executive Michael Fiddelke, who takes over from Brian Cornell in February, said performance was “in line with our expectations” despite “multiple challenges.” Translation for investors: the model works when guests buy groceries, toys, and fulfillment, and it hurts when they defer apparel and home discretionary.
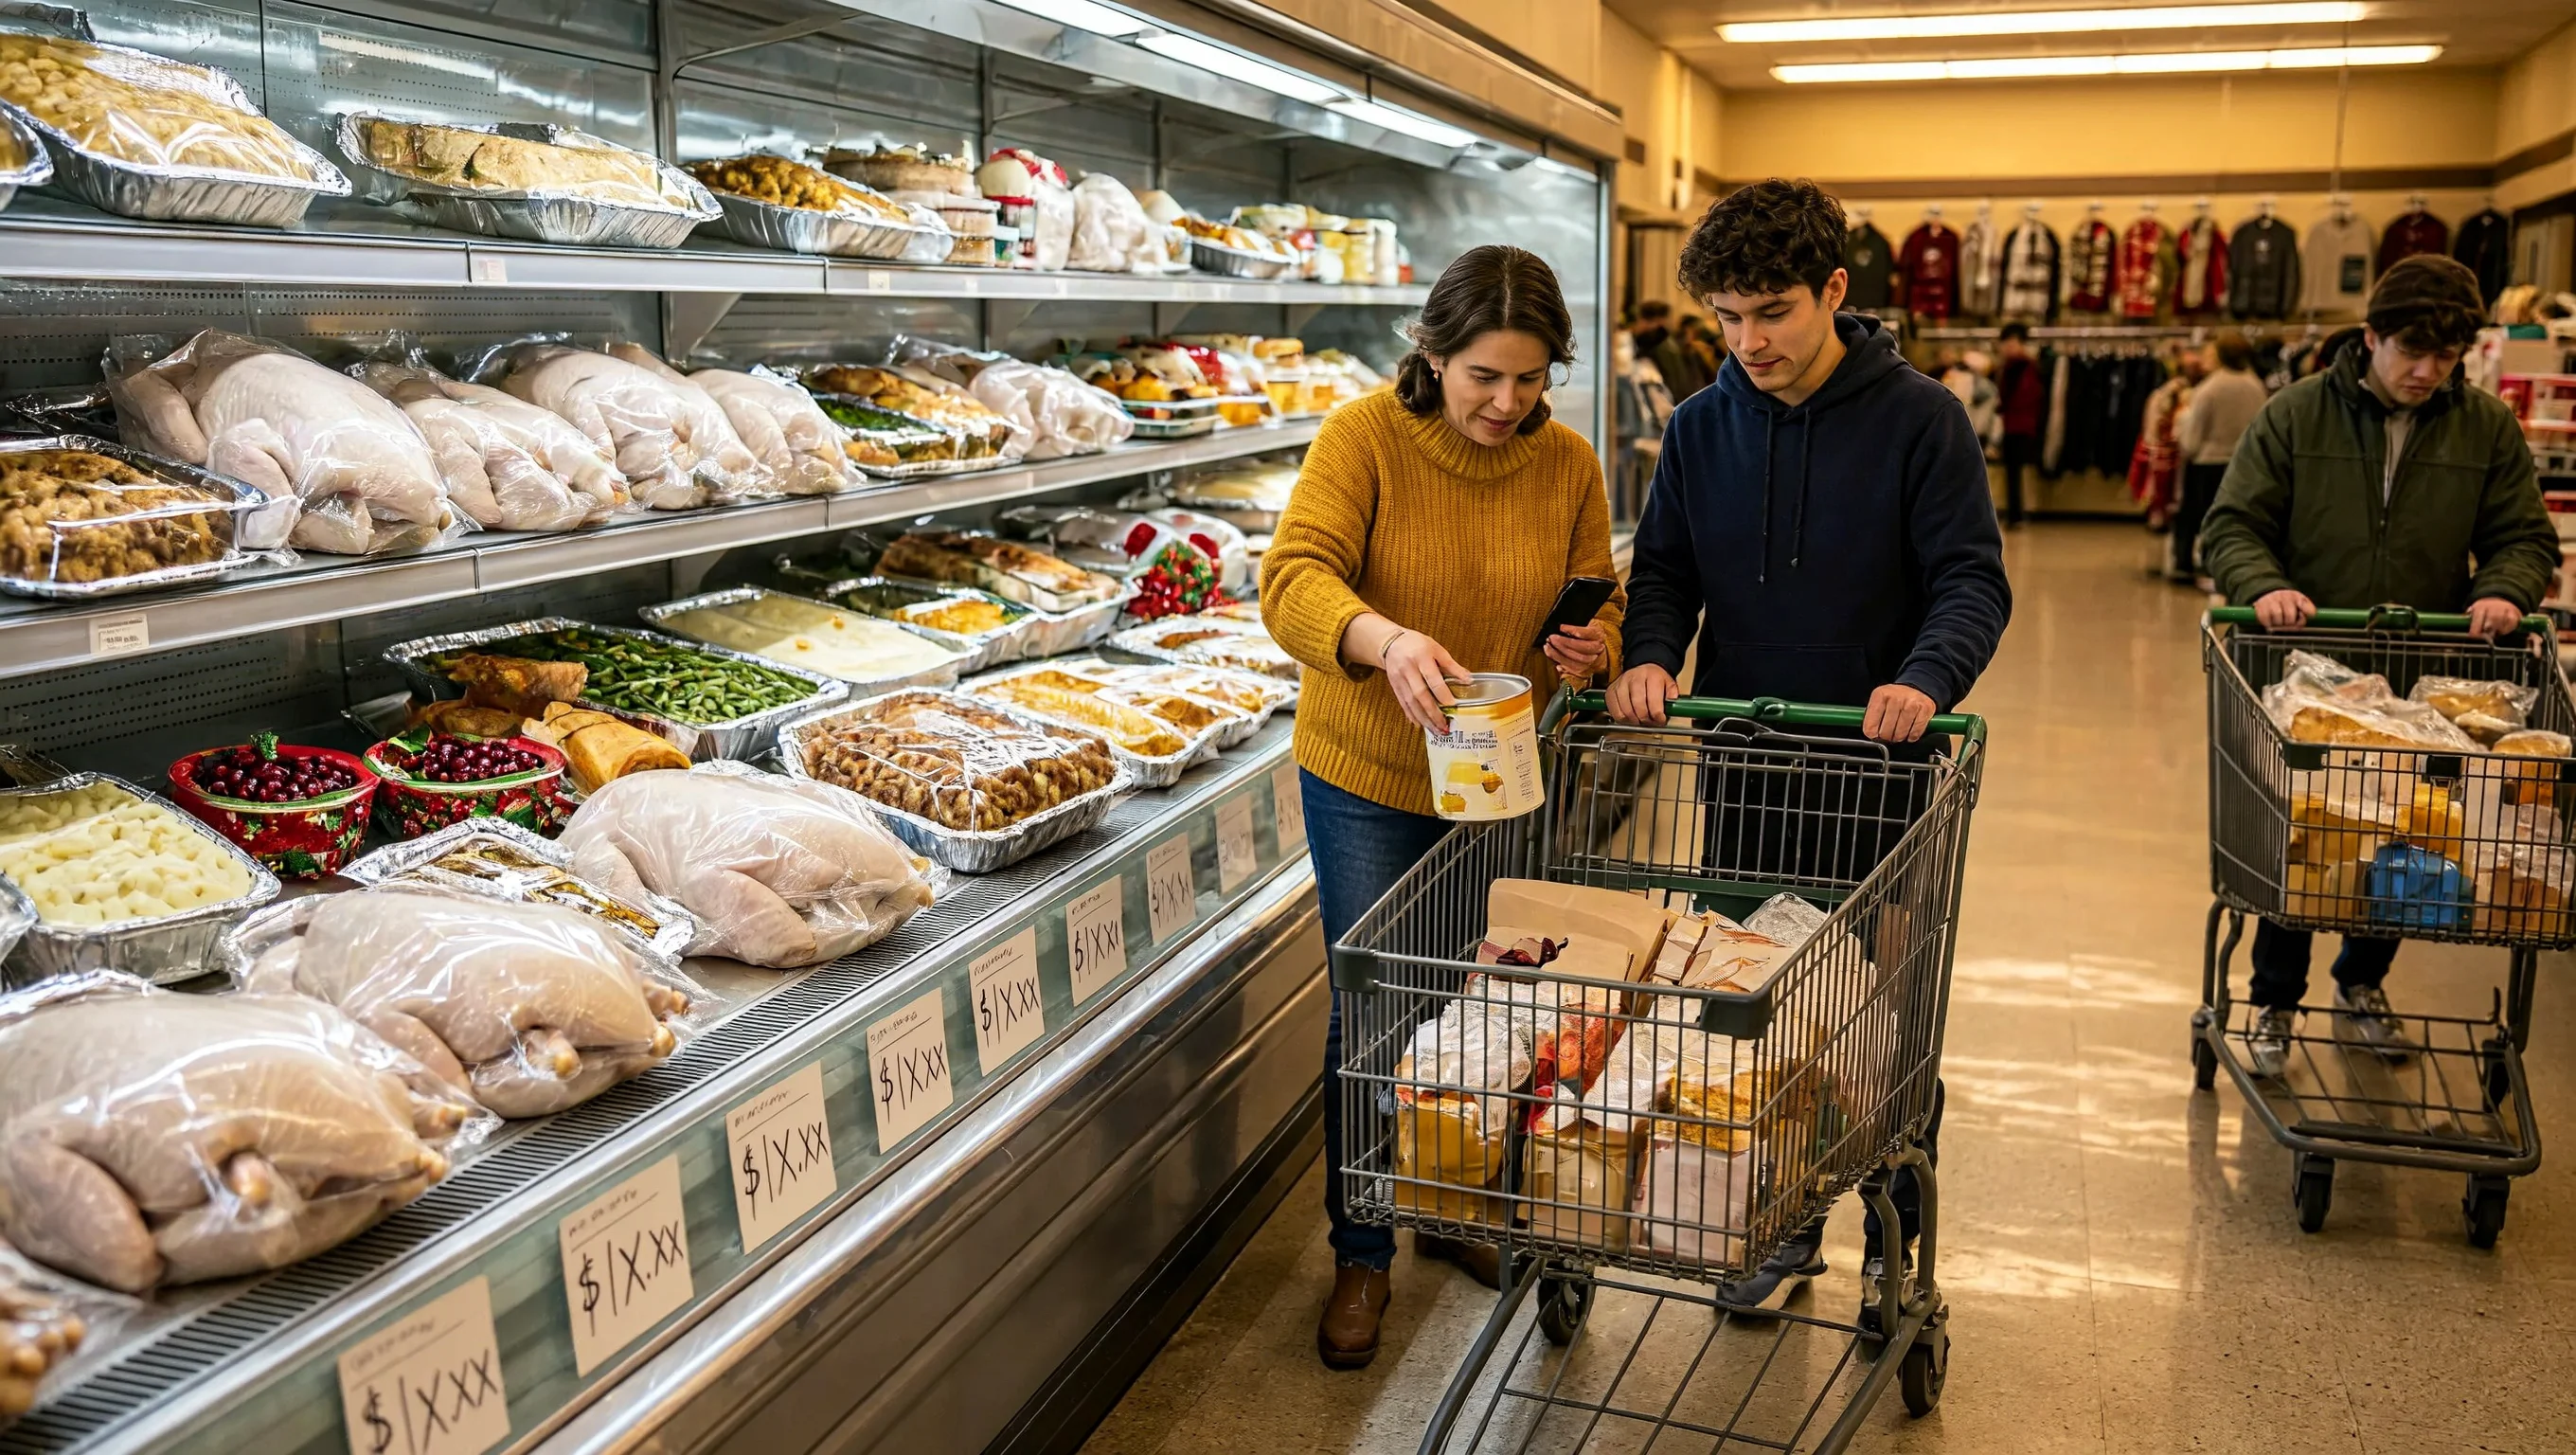
CAPITAL responded the only way a mature big-box can—by buying traffic. Reuters reported Target would pour another $1 billion into price cuts and experience investments to defend market share into holiday, on top of holiday merchandising that includes 20,000 new items and Thanksgiving meals for four under $20, with turkey advertised at 79 cents a pound in promotional materials. That is LABOR physics: when the median customer’s marginal dollar goes to food and fuel, the retailer subsidizes the trip with traffic drivers and absorbs margin.
Full-year adjusted EPS guidance tightened to $7.00–$8.00, trimming the top end by $1 from the prior range. Fourth-quarter sales are still expected to decline low single digits—a cautious setup into the peak gifting weeks even as TJX and Lowe’s posted stronger comps the same morning, underscoring that execution and category mix, not macro alone, separated winners.
Target’s same-day delivery growth is a logistics win. It is also a tell: the customer who still spends wants speed on necessities, not an extra lap through home décor.
Non-merchandise revenue rose 17.7 percent, with Roundel advertising, membership, and marketplace fees all growing double digits. That flywheel matters: when product margin compresses, media and data revenue becomes the quiet offset—PLATFORM economics inside a brick-and-mortar shell.
Balance sheet still has room—to a point
Target returned $518 million in dividends and repurchased $152 million of stock in the quarter, retiring 1.7 million shares at an average $91.59. After-tax ROIC over the trailing twelve months fell to 13.4 percent from 15.9 percent—not a crisis, but directionally consistent with heavier markdowns and softer comps.
Shares sold off in the session as the top line lightened, even though management framed the quarter as controlled damage. For allocators, the debate is whether the $1 billion reinvestment buys durable traffic or trains customers to wait for promotions—a classic CAPITAL versus LABOR trade when real wages grow unevenly and Fed policymakers admit spending strength clusters at the top of the income ladder.
Holiday read-through
For the consumer economy pillar, Target is a middle-income lens—not luxury, not dollar-store. Wednesday’s print confirms the K-shaped pattern without requiring jargon: comps negative at the chain level, positive in food, positive in digital fulfillment, negative in stores where discretionary dwell time used to convert.
Watch inventory shrink improvements and supply-chain efficiency gains management cited; they are real savings, but they do not replace full-price fashion volume. Watch tariff commentary on the call for forward cost pressure on imported housewares—the same STATE channel the Fed minutes worried could keep services inflation sticky even as goods baskets soften.
The synthesizing line for readers sitting beside a sharp allocator: Target is not failing. It is reallocating margin to meet a customer who arrives for 79-cent turkey and leaves without the throw pillows. Until discretionary confidence broadens beyond the upper cohort the Fed described hours earlier, that is the binding constraint—and $1 billion is the price of pretending otherwise for one more holiday season.
Continue reading


Sources
Target Corporation Q3 2026 earnings release and conference call materials; Reuters retail coverage November 19; Culled consumer-economy barbell reporting.


