

Roughly half a million people marched on Saturday over living costs, and the weekend turned violent: nearly 2,400 arrests, almost 1,000 injured police, Limoges city hall set ablaze. Interior Minister Laurent Nunez said forces had lost control in several cities; Prime Minister Sébastien Lecornu called for localized curfews and refused to rule out a state of emergency. French OAT spreads remain near crisis-era wides from early October. The new risk is operational—whether Paris can still impose the tax and spending choices bondholders are pricing while restoring order on the street.
Sovereign spreads told investors France had a fiscal-credibility problem. Street disorder and coercive crowd control now threaten the parliamentary arithmetic behind the fix.
UPDATE — 19 October 2026: Weekend cost-of-living marches escalated into some of the worst urban violence France has seen in years. Authorities reported nearly 2,400 arrests and almost 1,000 injured police and gendarmes; DW reported Interior Minister Laurent Nunez’s admission that forces had lost control in several cities, while Prime Minister Sébastien Lecornu urged localized curfews and left a state of emergency on the table. The sections below retain early-October market context on OAT spreads and the euro; the binding question now is whether Paris can pass consolidation while managing the street.
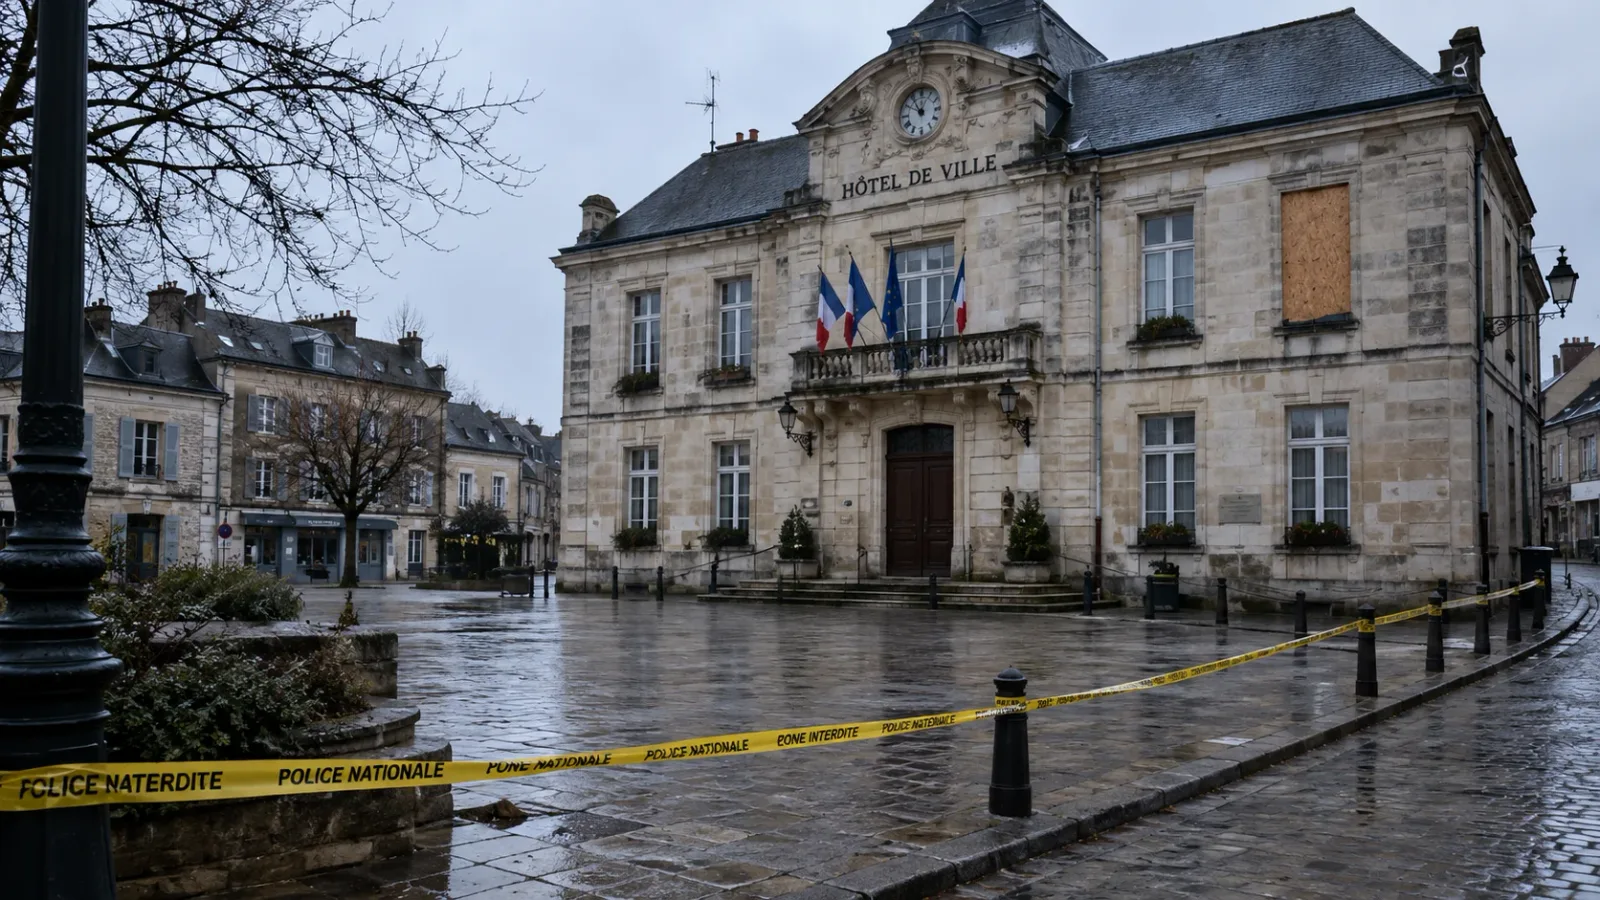
France’s fiscal stress is no longer visible only on bond screens. It is visible in burned cars outside provincial city halls, in Marseille’s midday ban on gatherings, and in a president demanding accountability from an interior minister he will not sack.
The CGT union put nationwide turnout at about 500,000 on Saturday—organizers pitched the mobilization as a revival of Yellow Vest-era pressure six months before the presidential election. Most marches were peaceful; parallel crowds of masked youths looted shops, torched property, and clashed with police. Limoges’s historic hôtel de ville burned. Paris saw torched vehicles and student blockades at the Louvre and Sciences Po. Macron condemned “failures in anticipation and intelligence” but kept Nunez in post after the minister offered his resignation, ordering new operational methods for handling violent factions without conflating them with lawful protesters.
Lecornu emerged from a Monday crisis meeting insisting he would “restore order.” He asked municipalities to impose very limited, localized curfews rather than a blanket national lockdown, and said curfews looked “better suited” to the situation than an immediate state of emergency—while refusing to rule the emergency out. Marseille banned demonstrations from noon to 8 p.m. that day. The choreography matters: every hour spent on crowd control and political blame is an hour not spent on the 2027 budget arithmetic that investors have been punishing since September.
From Spread Shock to Execution Risk
When this piece first published in early October, the clean read was market plumbing: French 10-year OAT–Bund spreads near 140–150 basis points, French yields pressing toward 5%, and the euro near a 17-month low around $1.116 even as soft U.S. payrolls eased Fed-hike odds. That was a credibility verdict on a 5.4% of GDP deficit projection, debt marching toward 119–122% of GDP, and a advertised €54 billion consolidation package in a fractured parliament.
Nothing in this weekend’s violence magically widens spreads on its own. The transmission is political and operational. Consolidation requires cuts and tax measures that hurt the same households protesting fuel and living costs. A minority government already juggling Article 49.3 risk and a looming 2027 election must now bargain with opposition parties while television loops show city halls on fire and a minister saying police lost control. Markets do not need proof that the budget will fail to demand a higher risk premium—they need only doubt that the votes and the social license exist to deliver the plan.
The falsifier is not “no more protests.” It is a budget vote that locks in measurable consolidation without fresh street escalation—and a narrowing OAT–Bund spread back toward the pre-blowout zone. Neither is in evidence yet.
European equity desks on Monday still listed French unrest beside global tech weakness in their risk ledgers; the fiscal channel remains analytical, not yet a second discrete sell-off. That caution is warranted. Reporting links unrest to pressure on French bonds and the euro, but no source establishes that the 2027 text will be defeated. The residual is narrower: execution friction—the cost of passing unpopular measures rises when the state’s monopoly on order looks contested.
What Parliament Still Has to Do
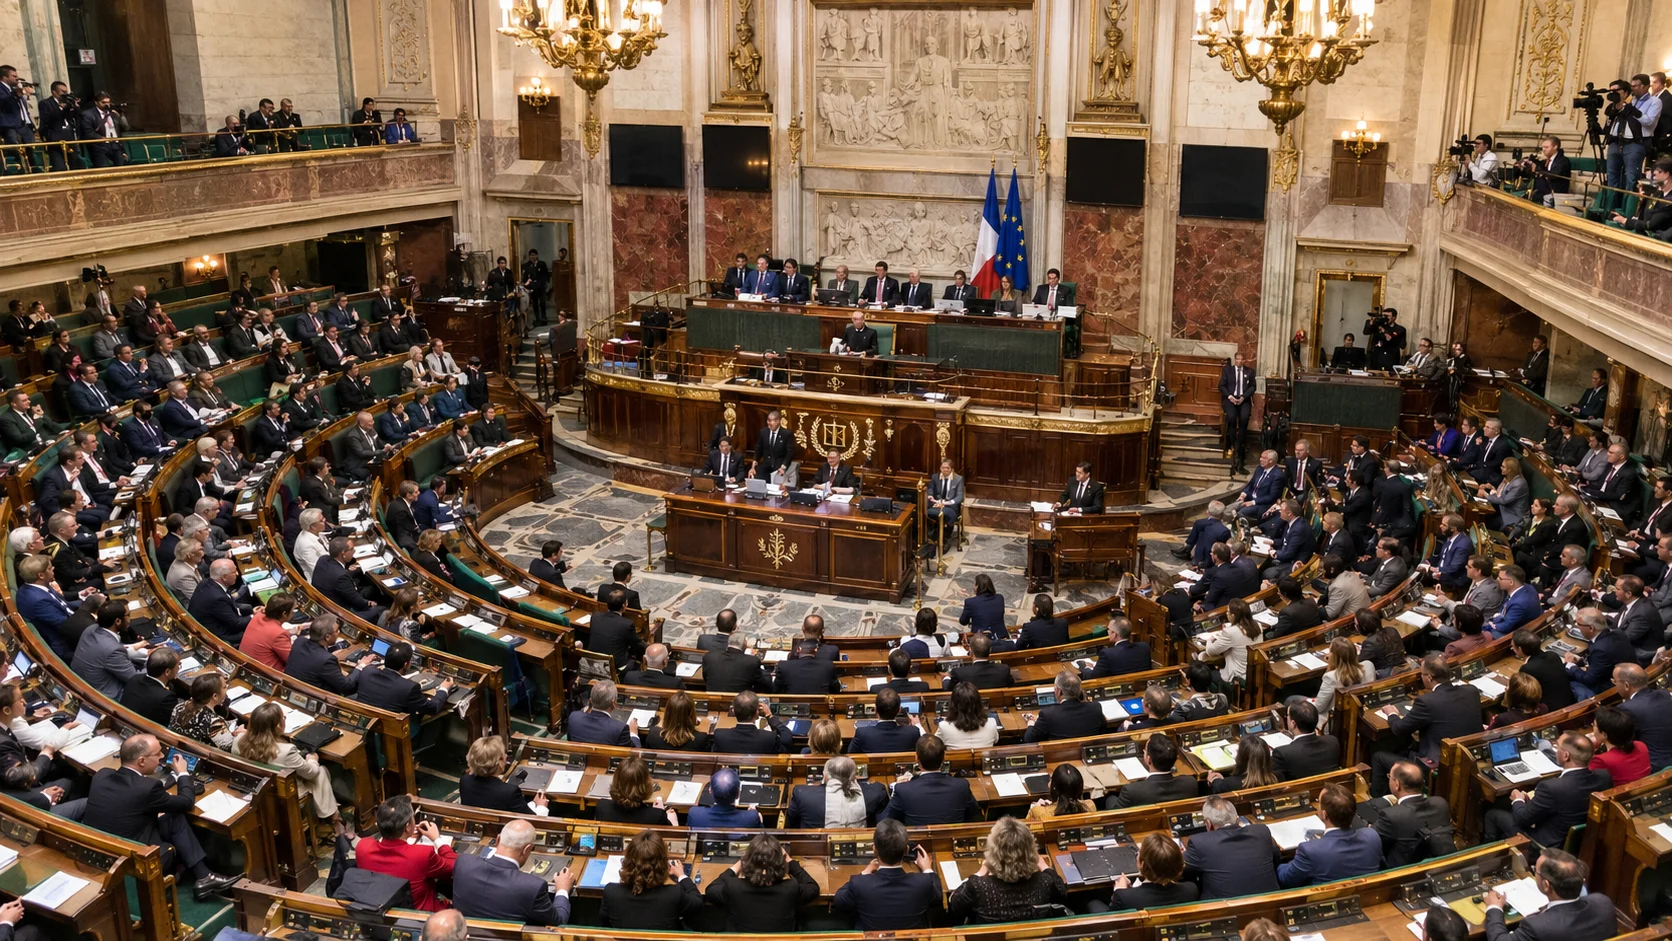
Lecornu’s government has not withdrawn the consolidation story. The advertised path still aims to drag the deficit from 5.4% toward 5% next year through spending restraint and revenue measures that land on pensions, local government, and high-income households in various drafts circulating in Paris. Passing that text requires either a workable coalition bargain or forced passage—each harder when Macron’s interior minister is a lightning rod, Jean-Luc Mélenchon’s France Unbowed is accused by the far right of legitimizing chaos, and Marine Le Pen’s National Rally frames the violence as proof of elite failure.
The ECB’s dilemma, sketched in October, does not disappear. Wider French spreads still tighten financial conditions without a rate move and can drag periphery trades when France/Italy-long, Germany-short books are cut—see Lagarde’s warnings on market-structure stress for the separate plumbing channel. But the Bank cannot substitute for a budget. Soft U.S. data may slow the Fed; it does not write French tax law or staff French riot units.
Opposition leaders will price the government’s weakness. Investors will price the same weakness through OATs that remain expensive versus Bunds. The October spread blowout established that French paper is no longer a quiet carry trade against Germany. October’s street violence establishes that the repair job is not only a spreadsheet—it is a test of whether the French state can impose fiscal pain while convincing citizens and bondholders alike that it still controls the cities where those choices bite.
Continue reading


Sources
DW reporting on Oct. 19, 2026 unrest, curfews, and Macron–Nunez response; CGT turnout estimate; prior market levels on OAT–Bund spreads and EUR/USD from early-October 2026 coverage; French deficit projections from government statements.


