

Global families are building a portfolio of places — Dubai for scale, Hong Kong for Asian liquidity, Singapore for services — not a single exit. Q2 super-prime sales and September’s Hong Kong auction calendar show property and art working as real-time capital-migration instruments.
The conventional story treats wealth flight as a single decision: leave London, buy Dubai, done. The Q2 2026 tape looks more like portfolio construction across jurisdictions — property at the $10 million-plus tier, services layered on top, and Hong Kong’s September art calendar offering a liquid parallel market for the same clientele.
Knight Frank’s Global Super-Prime Intelligence report (16 September 2026) counted 572 sales at $10 million-plus globally in the second quarter, down 7% quarter-on-quarter and 6% year-on-year. The headline is not collapse but reordering: momentum spread across Asia, the Gulf, and selective U.S. hubs while the old “one trophy mansion” model loosens.
The Q2 scoreboard
Dubai kept first place on both count and value — 131 sales worth $2.17 billion — but cooled sharply from an exceptional first quarter: −21% by volume and −27% by value quarter-on-quarter. Versus Q2 2025, Dubai was −8% on count and −17% on value. Knight Frank reads that as the first clear evidence of moderation after H1’s record pace, with regional geopolitical instability cited as a swing factor — without erasing Dubai’s 12-month lead (541 transactions, $9.66 billion in the year to June).
Hong Kong ranked second: 93 sales, $1.67 billion. Transaction counts were nearly flat from Q1; value slipped 9% quarter-on-quarter. The longer arc is what matters for the redundancy thesis: +75% on count and +67% on value versus Q2 2025 — a recovery deep enough that industry coverage (including SCMP, 25 September 2026) framed Hong Kong as closing the gap with Dubai even as Middle East security risk repriced Gulf sentiment.
Singapore continued to strengthen: 45 sales worth $715 million, up 7% in count and 15% in value from Q1 — smaller in absolute dollars but consistent with the “back office + residence” leg of a three-hub stack.
The index is not a three-city story alone. London posted 44 sales but $1.43 billion in value (+72% quarter-on-quarter), with average deal size near $32.6 million — a burst at the very top, not broad volume. Miami rose to 53 sales ($808 million); New York cooled to 57 sales ($965 million) from Q1. Capital is bar-belling: practical boltholes and rental liquidity in familiar cities, plus Gulf and Asian hubs for tax, timezone, and deal flow.
Migration numbers versus mansion numbers
Henley & Partners’ Private Wealth Migration Report 2025 (published ahead of the 2025 calendar year) projected a net inflow of about 9,800 millionaires to the UAE — described as the largest national inflow in the study’s history, with roughly $63 billion in associated investable wealth. That figure measures people relocating, not every dollar already parked in Palm Jumeirah penthouses. It belongs in the same frame as super-prime sales: formal residency and informal property are complementary channels.
Nine of Henley’s top ten projected destination countries operate structured investment migration programs; the UAE’s success is packaged as visas plus lifestyle plus business environment, not a deed alone. Dubai’s own super-prime market still drew 296 $10 million-plus homes in H1 2026 (Knight Frank UAE, July 2026) — proof that migration and trophy residential demand can run together until geopolitics or supply interrupts liquidity.
Inference: families are buying optionality — a Dubai operating base, Singapore governance and family-office infrastructure, Hong Kong exposure to Asian capital markets and collectibles. Counterevidence: concentrated new supply in Gulf beachfront inventory, Hong Kong secondary discounts on non-super-prime stock, and any quarter where Dubai’s Q2-style cooldown persists can look like “exit” when it is really rebalancing.
Turnkey boltholes and the rent bid
Knight Frank’s “dip in and dip out” mobility piece (18 September 2026) argues the mobile wealthy now prioritize flexibility, services, and liquidity over a single sprawling villa. Oliver Banks, on the firm’s international residential team, describes turnkey branded residences — often with private clubs — as the structural answer for clients spending fewer than 90 days in any one jurisdiction.
The numbers behind that lifestyle are concrete. Branded residence schemes grew from 354 globally in 2015 to 903 by end-2025, passing 1,000 in 2026 with on the order of 170,000 units (Knight Frank Residence Report, cited in the same article). Boutique city schemes in Miami, New York, Singapore, and Dubai trade on rarity and managed exit — the liquidity promise owners want when they are not resident year-round.
Where ownership friction rises — UK tax reform and “WEXIT” narratives show up repeatedly in Henley’s 2025 release — top-tier rent absorbs nomadic capital instead. Knight Frank cites five-year prime rent growth of 63% in New York, 53% in London, and 48% in Singapore. Rupert des Forges’s London desk anecdote captures the behavioral shift: clients who once allocated $30 million to a primary trophy now target ~$15 million for a practical bolthole, then Tuesday-to-Wednesday presence in London and weekends elsewhere.
That is the next luxury cycle in one sentence: managed, turnkey, liquid “boltholes” over one immovable status symbol.
Hong Kong’s September liquidity channel
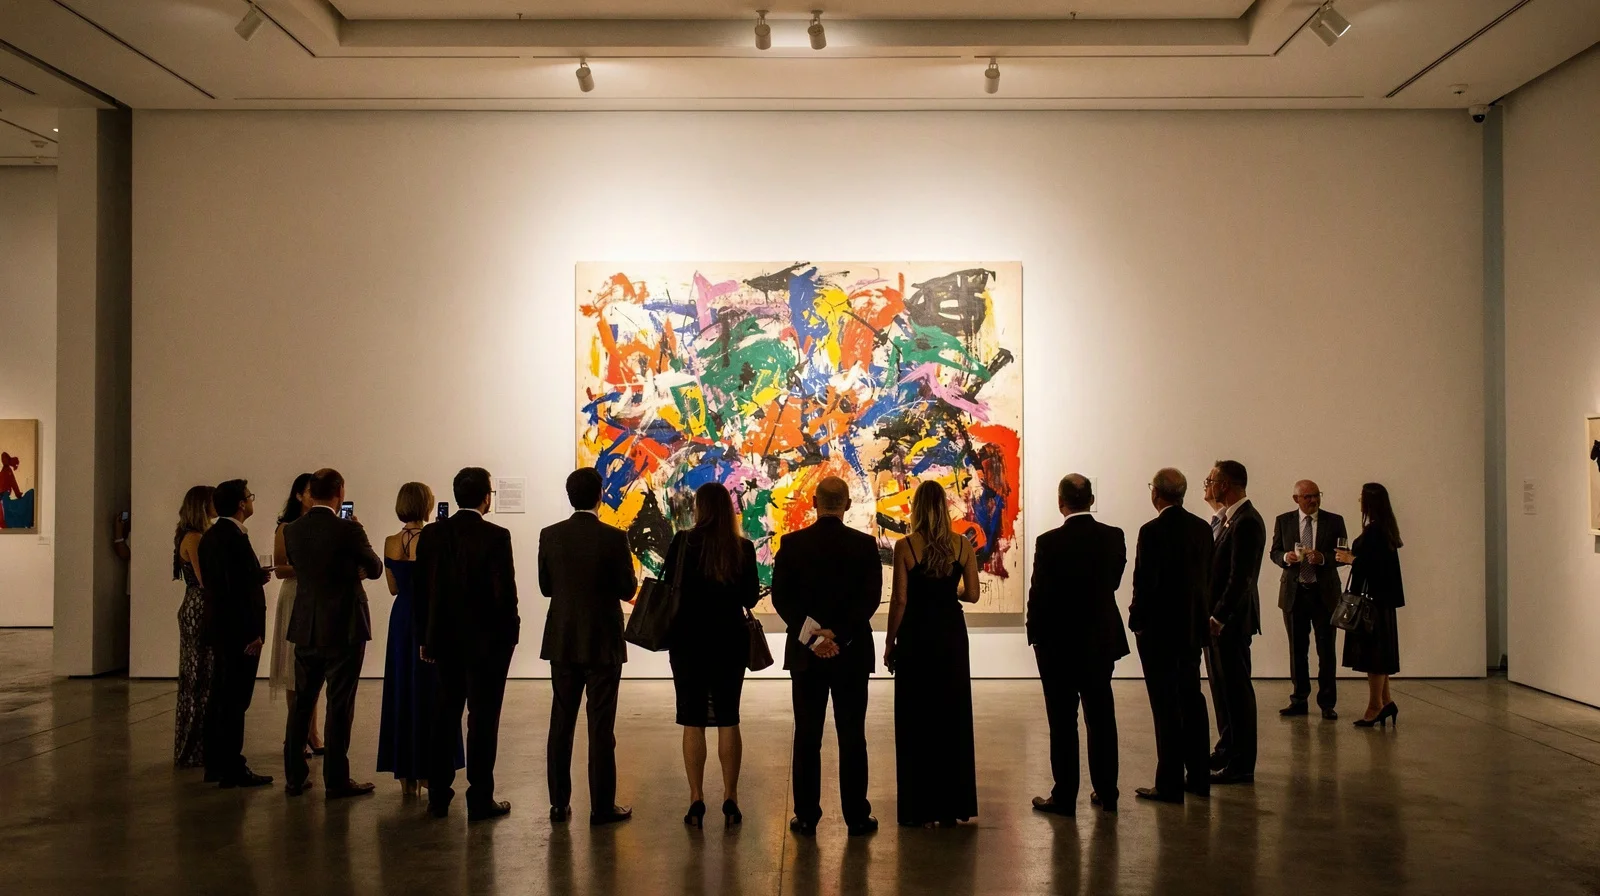
Property is not the only real-time migration instrument on the calendar. Sotheby’s Hong Kong season runs an exhibition 22–29 September ahead of a 28 September evening sale and 29–30 September auctions (house calendar, September 2026). Christie’s opened public preview 22–29 September at The Henderson, with live 20th/21st Century sales 29–30 September (press release, 8 September 2026).
The evening catalog is built for global cross-bidding: a Basquiat estimated at HK$56–76 million, a debut Kusama pumpkin at HK$48–68 million, Zao Wou-Ki and Richter abstractions in eight-figure Hong Kong dollar territory, plus a Rubens landscape with long institutional provenance — the sort of mix that turns a harbor city into a capital switch for collectors already owning flats in Mid-Levels or serviced apartments in Singapore.
Art liquidity does not replace super-prime illiquidity; it rhymes with it. Both are ways to store optionality where law, banking, and social graph align. For investors tracking the multi-hub thesis, bidder geography in these sales is as informative as hammer prices — especially when Dubai’s Q2 super-prime value step-down coincides with Gulf risk headlines.
What to track next
The due-diligence list is operational, not philosophical:
- Flight and FBO volumes into DXB, HKG, and SIN during sale weeks versus baseline — does physical presence match transaction counts?
- Family-office incorporations and private-bank hiring in Singapore and Abu Dhabi — back-office redundancy shows up in headcount before it shows in residential medians.
- Branded residence absorption and resale spreads in Dubai beachfront submarkets — supply can compress trophy liquidity even while net migration stays positive.
- Hong Kong secondary discounts outside the $10 million-plus tier — recovery at the top does not automatically lift the broad market.
- Art auction clearance and underbid rates this week — a soft Hong Kong season would challenge the “Asian liquidity leg” narrative without touching Dubai’s annual totals.
Policy, tax, rates, and regional security remain swing factors through second half 2026, Knight Frank’s central question for the index: whether breadth (London value bursts, Miami count, Singapore steadiness) can offset moderation in the markets that carried 2025–26 growth.
The elite response to geopolitical uncertainty is not a dramatic exit narrative. It is redundancy: multiple hubs, smaller footprints, services switched on and off, property and art each carrying a different half of the same balance sheet. Dubai can lead the league table and still cool quarter-on-quarter; Hong Kong can surge versus 2025 and still live inside a global index down single digits. Read together, that is not contradiction — it is diversification, the same instinct applied to cities instead of sectors.
Continue reading


Sources
Knight Frank Global Super-Prime Intelligence Q2 2026 (16 Sep 2026); Knight Frank The View on dip-in mobility and branded residences (18 Sep 2026); Henley Private Wealth Migration Report 2025; Christie's Hong Kong autumn 2026 release (8 Sep); Sotheby's Hong Kong sales calendar (Sep 2026); SCMP coverage of HK super-prime vs regional risk (25 Sep 2026)


