

By mid-afternoon on October 23, the Dow was down about 1.1 percent while the Nasdaq barely moved, Brent crude traded near $116.55, and traders were weighing Iran escalation, December Fed odds, and whether hyperscaler earnings can justify the AI build-out. The binding force is capital repricing a stagflationary chain—not merely fear of another headline.
The afternoon of Friday, October 23 did not look like a clean repeat of Thursday’s technology liquidation. Around 3 p.m. Eastern, reported snapshots showed the Dow Jones Industrial Average off roughly 1.1 percent (on the order of 600 points), the S&P 500 down about 0.5 percent, and the Nasdaq Composite nearly flat at −0.1 percent. Brent crude was quoted near $116.55, up about 3 percent on the session; WTI near $103.30, up roughly 3.9 percent. Breadth was weak, energy outperformed, and financials plus consumer-facing names absorbed more of the damage than the megacap complex.
That composition matters. If the only story were geopolitical panic, you would expect yesterday’s AI duration trade to keep leading lower. Instead, semiconductors were stabilizing while the index weighted toward old-economy balance sheets bore the brunt—suggesting markets are threading more than one needle.
Iran is still the first domino
The most consequential geopolitical bid remains Iran and the Strait of Hormuz. Reports of additional U.S. force posture, Iranian threats to regional infrastructure, and continuing disruption around the choke point keep a war premium in crude. Flows through Hormuz are reportedly still well below pre-crisis norms—on the order of roughly one-quarter below prewar export levels in recent Culled and wire estimates—so the fear is not merely another exchange of strikes but whether energy exports stay dependable through winter logistics.
The calendar adds friction. Israel’s October 27 election and the November 3 U.S. midterms sit inside the same two-week window traders are using to handicap whether military posture hardens or eases. Culled’s midterm-versus-market clock piece argued that portfolios can wait for clarity voters cannot; today’s tape is the capital-markets echo of that mismatch—oil moving now, ballots fixed soon.
Oil is inflation again, not background noise
At $117-ish Brent, energy is no longer a line item equity bulls can wave away. Higher crude feeds transportation, manufacturing margins, and household expectations—the channel that complicates Federal Reserve math when the labor market is still tight enough to matter.
Futures markets were, by Friday afternoon, flirting again with the possibility of another rate move in December rather than a smooth glide toward disinflation. The 10-year Treasury yield hovering near 5 percent keeps financing conditions restrictive for everything duration-sensitive, including the AI build-out.
The AI trade has a credibility ledger
Thursday’s Nasdaq rout was as much about capex credibility as about Hormuz. Investors are asking whether revenue and productivity gains can cover hyperscaler spending and the debt that funds it—questions amplified when Meta telegraphed heavy infrastructure plans without delivering the relief bid bulls wanted.
Friday’s relative calm in tech does not settle the argument. Next week’s Alphabet, Microsoft, and Amazon earnings are the next stress test for whether “AI platform” remains a multiple story or becomes a cash-flow audit. Culled’s participation map for the NDX separated levered de-grossing from macro oil tax; today’s NQ-versus-Dow spread says macro is reasserting—but the earnings calendar can reopen the AI channel in hours.
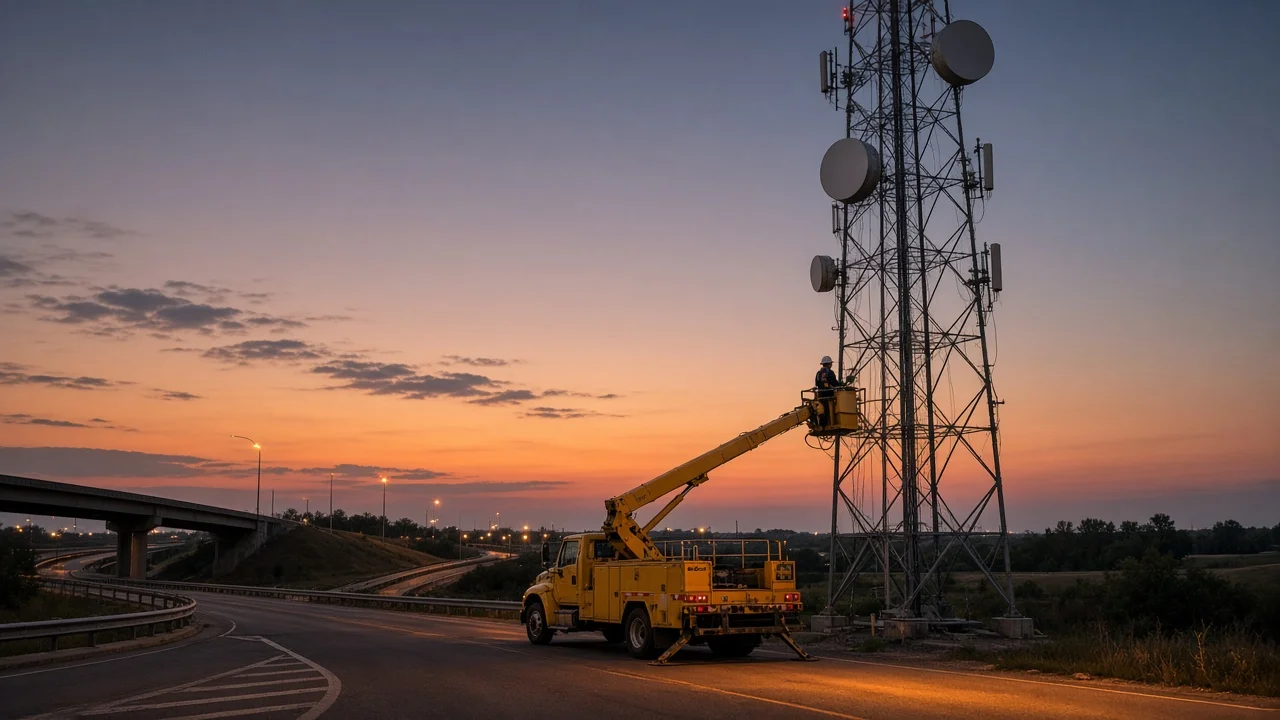
A fourth shock: SpaceX as wireless disruptor
Not all of the red on the tape was geopolitical. Reuters reported that speculation about SpaceX seeking thousands of cell sites for a potential fourth U.S. wireless carrier sent AT&T and T-Mobile down more than 6 percent in recent sessions, while SpaceX-linked equity markers moved the other way. That is a separate repricing of terrestrial spectrum and tower economics—the same strategic lane Culled traced when SpaceX bought low-band licenses to pair Starlink with a cellular layer in the Grain spectrum deal.
Wireless incumbents are therefore fighting a two-front sentiment war: oil-driven macro weakness and platform entry risk from orbit.
What Monday will test
| Signal | If it persists | What it implies |
|---|---|---|
| Brent holding $115–120 | Energy disruption stays an inflation threat | Margin squeeze outside the oil patch |
| 10-year near 5% | Financing stays tight | AI capex needs even stronger payback proof |
| NQ outperforming Dow | AI selling paused | Macro shock not yet generalizing |
| NQ lagging with oil up | Dual headwind | Stagflationary repricing deepening |
| Energy vs. airlines | Sector-specific oil shock | Less about a single headline |
The revealing detail is the Nasdaq holding up better than the Dow after Thursday’s tech drawdown. Energy leadership, weak breadth, and consumer pressure fit a market increasingly worried about a prolonged stagflationary squeeze: war risk lifts crude; crude revives inflation; inflation limits the Fed; restrictive rates make the AI investment boom harder to finance.
That chain can outlast any one diplomatic headline. The question for Monday is whether oil keeps rising while equities fall. If both trends stick, the case strengthens that investors are pricing a sustained economic shock—not a one-day geopolitical flutter.
Continue reading


Sources
Afternoon U.S. equity and crude price snapshots; Reuters on SpaceX cell-site speculation and carrier selloff; prior Culled coverage on Hormuz flows, NQ participation, and Starlink spectrum strategy.


