

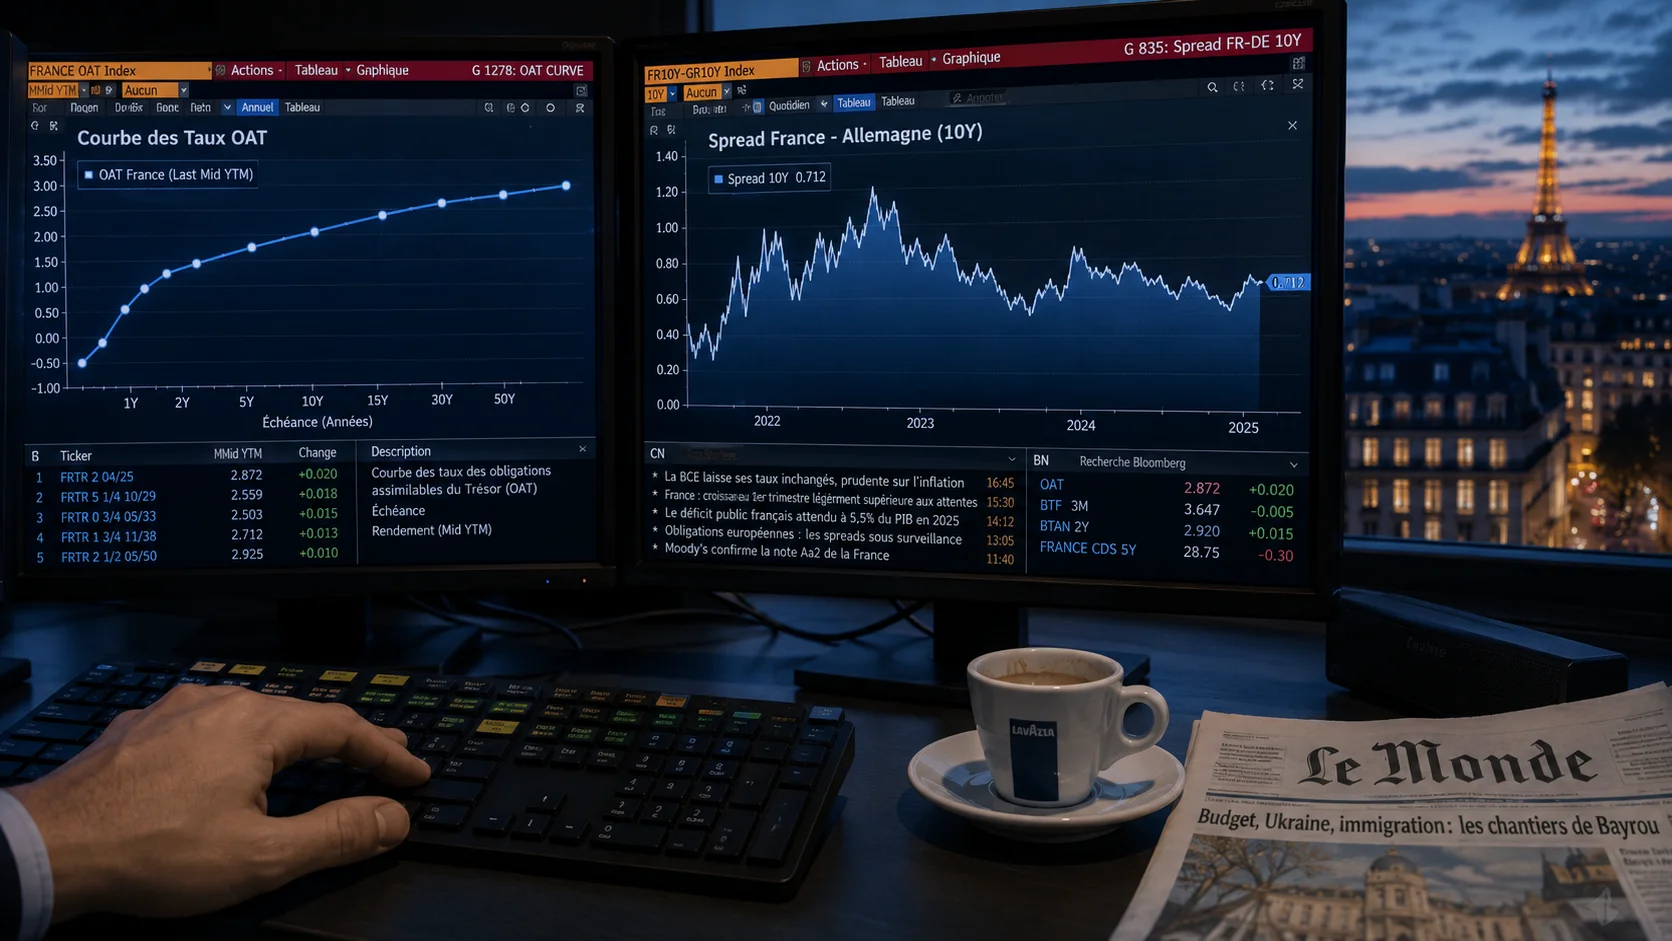
Moody’s affirmed France’s Aa3 sovereign rating on October 23 with a negative outlook, sparing a downgrade markets had priced. Benchmark 10-year OAT yields nevertheless remained above 5% and France-Germany spreads near 15-year highs as roughly 70,000 police deployed for nationwide protests and authorities tightened march routes after last weekend’s disorder.
France received a ratings reprieve and a market reprimand in the same breath. Moody’s left the sovereign at Aa3 on 23 October, keeping the negative outlook it assigned a year earlier, and said it assumes a deficit-reducing 2027 budget will be adopted. Bond investors were not reassured: the 10-year OAT had already traded above 5%, and the spread over German Bunds sat at a 15-year wide. On 24 October, Interior Minister Laurent Nunez put roughly 70,000 police and gendarmes on the street for a new day of marches — a security mobilisation that treats public order as fiscal infrastructure.
What Moody’s did — and did not — fix
Moody’s spared France the downgrade S&P and Fitch had already delivered, easing one cliff investors had priced. The agency’s language still described political fragmentation impairing legislation, social tension hampering deficit repair, and borrowing costs rising faster than prior assumptions. It could move the outlook to stable only if institutions narrow the deficit — while explicitly assuming financing costs and street tensions abate somewhat in coming months.
The finance ministry called the unchanged rating proof of budget credibility. Markets read the same file differently: Reuters cited a 5.14% 10-year yield on 23 October, the highest since July 2002, with risk premia over Bunds at levels last seen in 2011. That is the gap between an agency label and the price of rolling more than $1 trillion of maturing debt before 2030.
Saturday’s order test
Authorities prepared for repeats of last weekend’s looting and vandalism on the edges of cost-of-living protests. Nunez warned that calls for violence circulated online; President Emmanuel Macron held a defence council and met student unions as demonstrations spread beyond the initial school-funding grievance.
By midday 24 October, Paris police described the situation as calm, while Nunez reported 135 arrests nationwide and seizures of improvised weapons, fireworks and other items on protest margins. Unions, students and Yellow Vest networks marched under heavy security; préfecture orders and route disputes — including contested paths in the capital — kept administrative law in play alongside riot shields.
An orderly day would narrow the near-term risk premium; disorder would feed directly into the budget politics Moody’s says must improve. Culled already framed how street violence becomes a budget-execution problem and how the 5% OAT threshold turns disorder into a funding benchmark. This weekend adds a live test of whether those lines move in opposite directions.
A Monday checklist for investors
Four signals matter more than the headline Aa3.
OAT–Bund spreads after the march — do they retrace Thursday’s widening or embed a higher political premium?
Budget procedure — the National Assembly resumes tax debates 27 October; can the government pass savings without a confidence collapse?
Agency convergence — does Moody’s hold encourage S&P/Fitch stability, or do spreads force the next review anyway?
Calendar risk — union-backed strikes are scheduled for 5 November, so one calm Saturday does not close the labor channel.
France’s rating was held; its political risk premium was not cleared. Until spreads and streets move together, sovereign funding remains a protest story as much as a spreadsheet story.
Continue reading


Sources
CNBC and Reuters on Moody’s Oct 23 review; France 24 and AFP on Oct 24 security deployment and arrests; prior Culled reporting on OAT threshold and budget execution.


